Guatemala’s Credimujer Grants Q17.38 Million in Business Loans
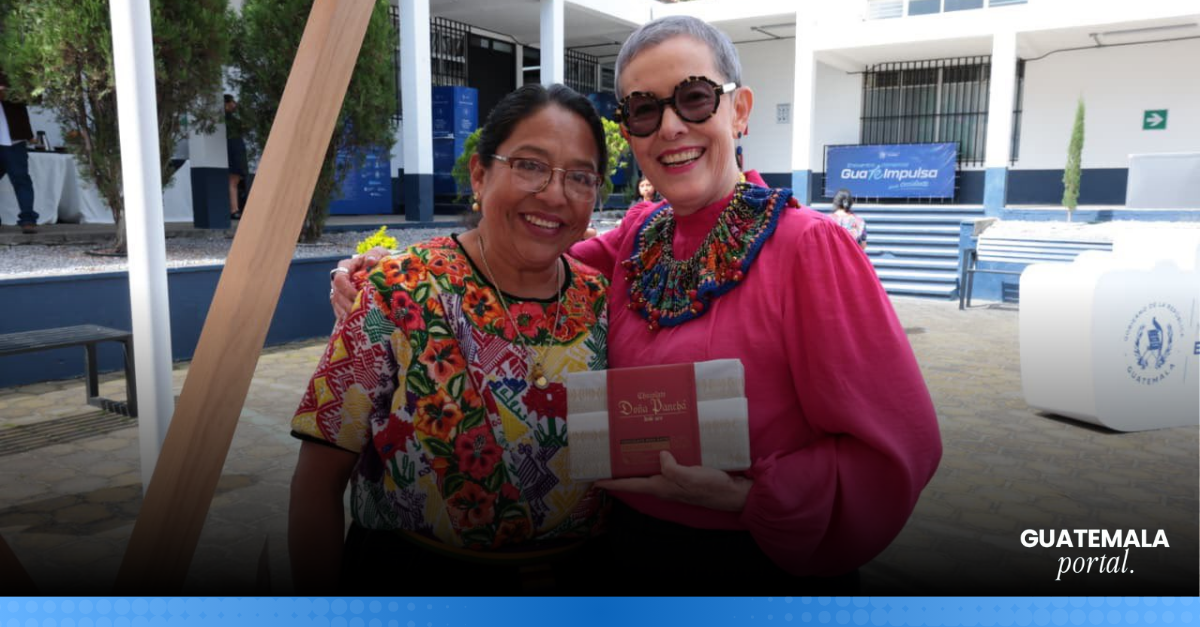
Guatemala’s Ministry of Economy (MINECO), operating through the Viceministerio de Desarrollo de la MIPYME, has continued to advance the Credimujer funding mechanism to expand access to capital for female entrepreneurs across the nation. According to official reports from the Agencia Guatemalteca de Noticias (AGN), the program channeled Q17.38 million through 178 loans between January and September 2026. This performance builds upon a broader operational trajectory reported by MINECO in August 2026, which indicated that Credimujer accumulated a total of 281 credits amounting to Q26.69 million spanning activity from 2025 through 2026, with a physical presence reaching 17 of Guatemala's 22 departments.
Una nueva oportunidad de negocio puede llegar en cualquier momento. ¿Tu empresa está preparada para aprovecharla?
— Ministerio Economía (@MINECOGT) October 29, 2026
CREDIMUJER facilita el acceso a financiamiento con tasa preferencial para mujeres emprendedoras y empresarias.
A través del Viceministerio de Desarrollo de la MIPYME… pic.twitter.com/FtI3O9JPfl
Credimujer’s Lending Model and Eligibility
As detailed in complementary reporting by Infobae, the mechanism operates by partnering with qualified financial intermediaries tasked with evaluating local loan applications and executing disbursements. The program is specifically targeted at female proprietors of micro and small enterprises aged 18 and older. According to these operational guidelines, the financing enables business owners to acquire machinery, modernize operational processes, and invest in necessary working inventory to support their commercial activities.
Recent legislative oversight hearings conducted by the Congress of the Republic of Guatemala provided a deeper financial breakdown of the fund's current standing. Congressional documentation indicates that the overarching fund possesses a total allocation of Q75 million. During these legislative sessions, authorities reported that 178 loans had been granted, totaling approximately Q17.3 million, under a financing scheme with an annual interest rate of up to 10%. While the program offers structured financing channels, this fixed rate drew scrutiny during legislative fiscalization, with a congressional representative questioning whether a 10% annual rate genuinely provides significant financial relief for micro-entrepreneurs operating under tight margins. Consequently, while the mechanism introduces structured lending channels, industry observers note it operates within a complex financing landscape rather than serving as an instantaneous remedy to structural credit barriers.
A Government Initiative for Women Entrepreneurs
Institutionally, Credimujer functions as a key component linked specifically to the Aceleradora Empresa Mujer under the broader framework of the Intersectorial Initiative for the Economic Empowerment of Women (IPEG). By focusing on this specific acceleration pillar, the program aims to strengthen the commercial viability of women-led enterprises without conflating its scope with separate governmental components focused on rural employment or distinct social initiatives.
Financial Inclusion and Access to Credit
The broader macroeconomic and market context surrounding the initiative centers primarily on addressing documented financial inclusion gaps for women in the domestic market. Historical studies and regional financial analyses consistently indicate that female entrepreneurs face distinct hurdles when attempting to secure formal business credit, often encountering higher collateral demands or limited access to traditional banking products compared to male business owners. By targeting micro and small enterprises across 17 departments, Credimujer addresses a critical segment of the Guatemalan economy where small-scale commercial ventures represent a vital share of local business formation.
Rather than projecting sweeping impacts on national gross domestic product or immediate export surges, economic analysts view the initiative through the lens of foundational financial integration. Expanding the availability of formal credit lines allows developing enterprises to stabilize operations, build formal credit histories, and gradually scale their commercial footprint. As MINECO and financial intermediaries continue to deploy the remaining capital from the Q75 million fund, the ongoing challenge for policymakers will lie in balancing sustainable interest rates with effective outreach, ensuring that women-led micro and small businesses across Guatemala can reliably access the liquidity required for long-term growth and market resilience.
Source: AGN